7% maximum drawdown, 3% intraday drawdown: What exactly is EagleTrader Max testing in traders?
When many traders judge whether their trading is stable, their first reaction is often to look at the equity curve.
Whether profits can be sustained, how large the maximum drawdown is, and whether results remain controllable after a strategy has run for a period—these data can indeed help us judge the performance of a trading strategy.
But true stability is not just about how much was ultimately earned.
Whether existing gains can be protected after becoming profitable, whether risk can be controlled in time during consecutive losses, and whether one can still trade according to established rules after a single-day change in condition—these also determine whether a trading system can operate over the long term.
In EagleTrader Max mode, this kind of trading stability is placed within a clearer dynamic risk control framework.
Max has set two core real-time risk controls: maximum drawdown risk control (7%) and intraday drawdown risk control (3%).
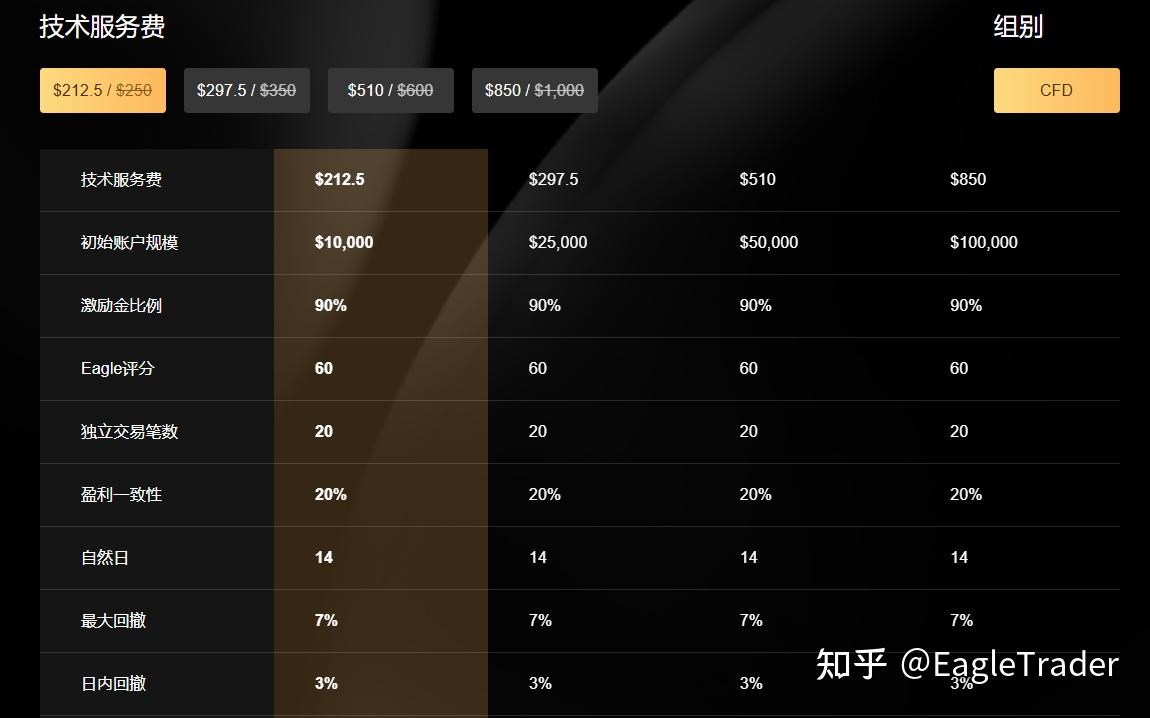
Unlike a fixed loss limit, these two risk control lines continuously change with account performance.
Traders not only need to generate profits but also continuously manage positions, protect profits, and control risk across different time scales as the account changes.
The 7% maximum drawdown tests whether the account can remain stable over the long term.
Max's maximum drawdown risk control line is dynamically calculated based on the account's historical high-water mark. The high-water mark here refers to the account's historical highest net value/balance (the maximum value) recorded in real time by the system, and it only rises and never falls.
Maximum drawdown risk control is triggered when the account retraces 7% of the initial account size downward from the historical high-water mark. The calculation formula is:
Maximum drawdown risk control line = historical high-water mark − initial account size × 7%
Assume a USD 100,000 account whose historical high-water mark rises to USD 109,000; then the maximum drawdown risk control line = 109,000 − 100,000 × 7% = 102,000 USD.
Once this line is touched, an account risk control violation is triggered.
This means that as the account continuously reaches new highs, the risk management requirements traders face will also change.
Being able to grow the account in the early stage only proves that a trader has the ability to generate profits;
After the account becomes profitable, whether positions can be reasonably controlled to avoid giving back a large amount of profit due to one aggressive trade or a loosening of risk standards better reflects whether the trading system is mature.
Therefore, the 7% dynamic maximum drawdown actually tests a trader's ability to manage positions, drawdowns, and profit protection over a longer cycle.
If a strategy can only obtain returns by relying on larger fluctuations, then as the account's highs continue to rise, hidden risks will become increasingly likely to be exposed;
Conversely, a trading approach that can adapt to the dynamic drawdown line over the long term often means the trader has developed relatively stable risk control habits.
The 3% intraday drawdown tests whether the trading rhythm can be maintained within a single day.
If the 7% maximum drawdown focuses more on long-term account performance, then the 3% intraday maximum drawdown further narrows risk control down to a single trading day.
The intraday high-water mark records the day's highest net value/balance from 00:00 platform time to 00:00 the next day, and it likewise only rises and never falls.
Intraday drawdown risk control is triggered when the account retraces 3% of the initial account size downward from the day's high-water mark. The calculation formula is:
Intraday risk control line = day's high-water mark − initial account size × 3% − user withdrawal (profit-sharing amount)
When the account reaches a new high during the day, the intraday risk control line is adjusted accordingly and recalculated on the new trading day.
Once this line is touched, the corresponding risk control action will likewise be triggered.
In particular, note that permitted withdrawals do not trigger intraday risk control; only the intraday risk control line is adjusted accordingly, while the maximum drawdown risk control remains unchanged.
This exemption clause prevents traders from being mistakenly judged as having committed a risk control violation simply because they withdrew profits normally.
The 3% intraday dynamic risk control does not merely restrict traders.
For example, the market goes smoothly in the morning and the account has already made some profit, but market conditions change in the afternoon.
If the trader, because of having already made money earlier, starts increasing position size and trading frequency in the hope of further expanding profits, then the profits already obtained may also be quickly given back due to a sudden increase in risk.
Another common situation occurs after consecutive losses.
A few stop-losses may not necessarily have a serious impact on the account, but if the trader keeps adding to positions and chasing orders out of eagerness to recover losses, a normal strategy drawdown may gradually turn into emotional trading.
What these situations truly test is whether a trader has a clear single-day risk boundary and whether, as profits and losses keep changing, the trader can always execute according to their own trading system.
These details are often difficult to see from the final profit figure alone, yet they are reflected very directly in the account's operation process.
The two dynamic risk control lines test two different kinds of stability.
Putting 7% and 3% together actually forms a complementary mechanism at two time scales: 7% guards against long-term loss of control, while 3% guards against a single-day collapse.
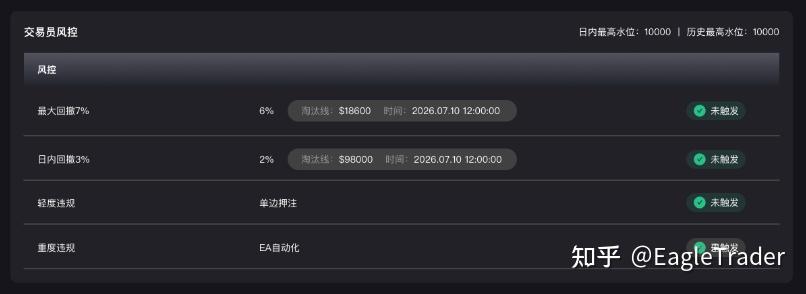
A trader may have a good long-term strategy, yet due to emotional loss of control after consecutive losses on a certain day, single-day risk management problems are exposed;
There are also traders whose daily trading looks very stable, but whose overall position structure is aggressive over the long term; only as the account's operating cycle continues to lengthen do the problems gradually emerge.
Therefore, Max mode's judgment of “stability” is not merely about whether a trader has reached a certain profit figure; it focuses more on the trader's sustained performance in daily risk, overall drawdown, profit protection, and position management.
Profit is the result; stability is the foundation of long-term trading.
For traders who have already established a mature trading system, these rules are actually very intuitive.
How much risk one is willing to take at most in a day, how to adjust position size after the account becomes profitable, when to stop trading during consecutive losses, and how existing profits should be protected—these rules that normally exist in a trading system will ultimately be truly reflected in the account results.
If you have sufficient confidence in your trading stability, you can also use EagleTrader Max to test your trading system within a clearer risk framework.
Ready to take on EagleTrader Max?
No upfront evaluation stage. Trade immediately once funded, with up to 90% profit split.